Does private health insurance in Portugal cover pre-existing conditions?
One of the most nerve-wracking moments I faced after moving to Lisbon was sitting in a sun-drenched cafe, staring at a ten-page medical questionnaire for a private health plan while nursing a chronic back injury. I remember the paralyzing fear that my history would make me uninsurable or leave me with a massive financial hole. This guide clarifies exactly how private insurers in Portugal handle pre-existing conditions and what options you truly have.
The Reality of Pre-existing Conditions in the Portuguese Private Sector
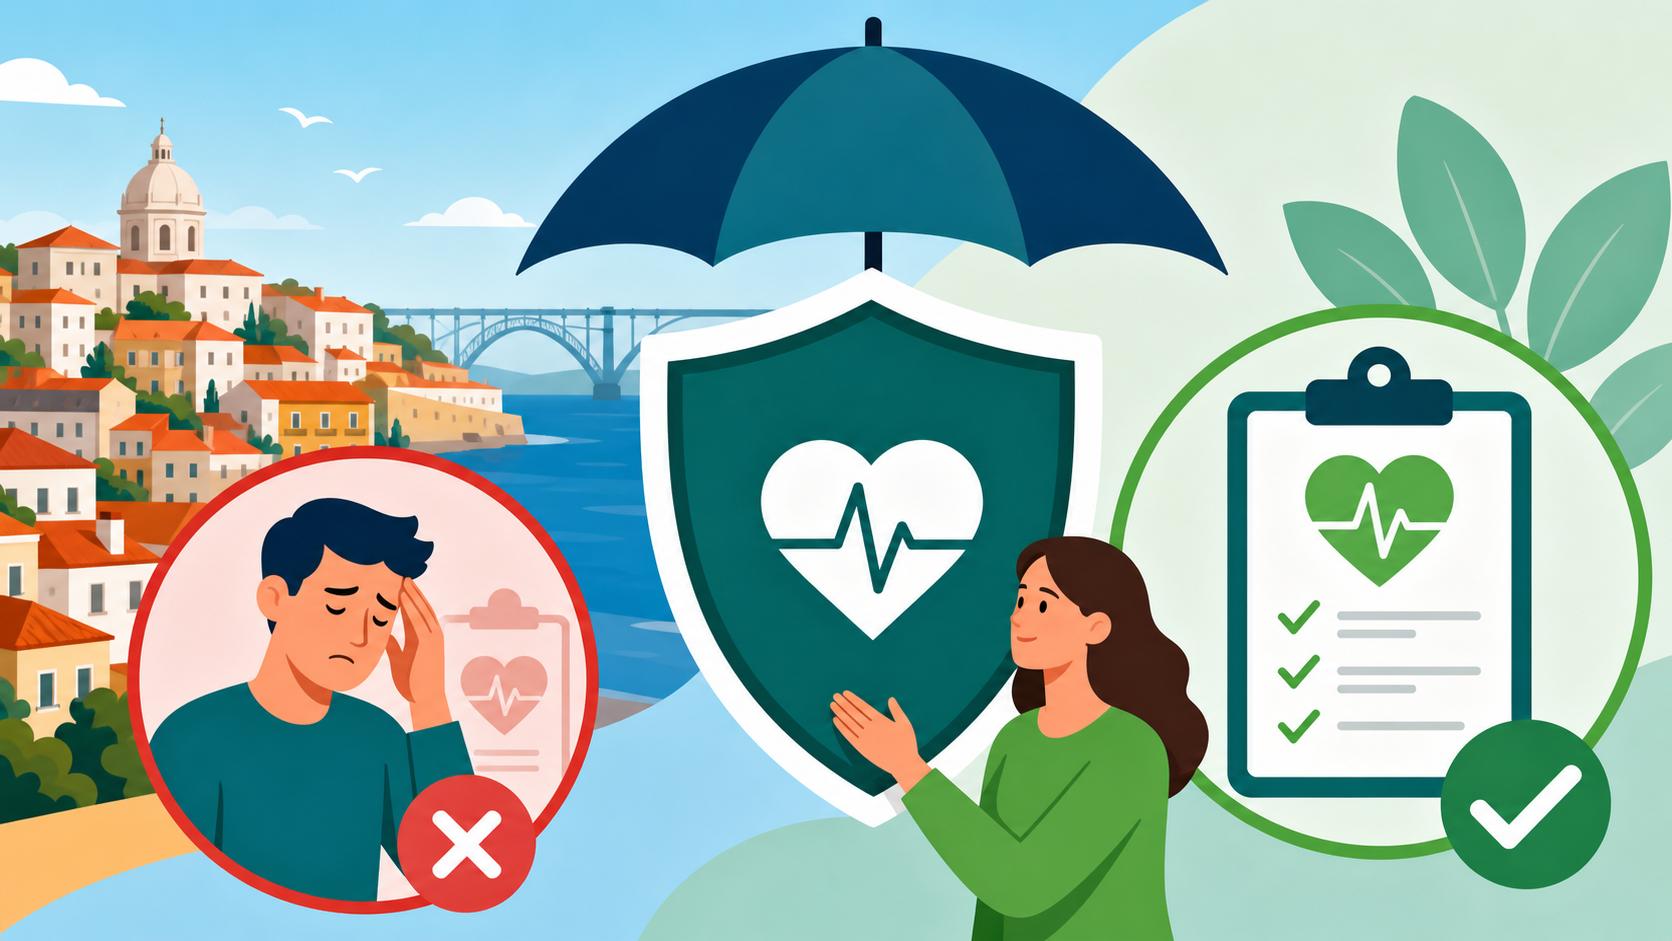
When you first dive into the world of private medical care here, you'll find that the term "pre-existing condition" (or doenças pré-existentes) is the single most important phrase in your contract. Unlike the public system, which is fundamentally inclusive, private insurers are businesses that calculate risk. In Portugal, the private market is highly competitive, but it remains traditional in its approach to medical history. If you have been diagnosed with a condition, sought medical advice for it, or even experienced symptoms of it before your policy start date, the insurer will categorize it as pre-existing.
The Infamous Medical Questionnaire
The gateway to any private policy is the Questionário Médico. This is a detailed document where you must disclose everything from a childhood asthma diagnosis to that knee surgery you had five years ago in London or New York. It is incredibly tempting to "forget" minor issues, but I strongly advise against this. Portuguese insurers are meticulous. If you later file a claim for a complication related to an undisclosed condition, they can—and often will—nullify your entire policy.
In my experience, the questionnaire is less about rejecting you entirely and more about defining the boundaries of their financial responsibility. They want to know if you are a "high-risk" client. For most expats, this means your policy will likely be approved, but it will come with specific riders or exclusions. Understanding Healthcare in Portugal for Expats: The Complete 2026 Medical Guide is the first step in realizing how these private nuances fit into the broader national scheme.
Defining Pre-existence Under Portuguese Law
Under Portuguese law, a condition is considered pre-existing if it was known to the insured person before the contract was signed. This includes conditions that were already diagnosed or those that, by their nature, could not have gone unnoticed. This is a bit of a gray area, but insurers generally look back at your medical records from the last five years. If you are moving from a country with digital records, assume the insurer could eventually gain access to that history during a major claim audit.
It is also vital to distinguish between a "Seguro de Saúde" (a full insurance policy) and a "Plano de Saúde" (a discount health plan). Discount plans, which you often see advertised for very low monthly fees, rarely ask for a medical questionnaire because they don't actually "cover" much—they simply give you access to lower negotiated rates at private hospitals like CUF or Hospital da Luz. For real coverage, you need a full insurance policy, which is where the pre-existing condition rules hit the hardest.
What Happens When You Declare a Condition: The Three Most Common Outcomes
Once you’ve submitted your medical history, the underwriting department will review your file. Unlike some other European markets, Portuguese insurers are quite binary in their decisions. You won't usually find much room for negotiation unless you are part of a large corporate group.
Total Exclusion of the Condition
The most frequent outcome is a "Specific Exclusion." This means the insurer will cover everything else—emergencies, new illnesses, broken bones—but they will explicitly state in your policy that they will not pay for anything related to your pre-existing condition. If you have chronic hypertension, for example, your visits to a cardiologist, your medication, and any complications like a stroke might be excluded from the private coverage.
This is why many expats choose to use a hybrid approach. They use private insurance for fast access to specialists and diagnostics for "new" problems, but they rely on the public system for the management of their chronic issues. You can learn more about how these two systems interact in our guide on Public vs Private Healthcare in Portugal: Which One Should Expats Choose?.
Agravamento: The Surcharge Strategy
In some cases, especially with premium providers or international plans like Cigna Global, the insurer might offer to cover the condition in exchange for a higher monthly premium. This is called an agravamento. While it makes your monthly "burn" higher, it provides the peace of mind that you won't be hit with a €20,000 bill if a chronic issue requires surgery at a private clinic in Porto or the Algarve.
For those with complex needs, Using Cigna Global or Allianz for international expat healthcare in Portugal is often a better route than local insurers. These international giants have more sophisticated underwriting processes. They might offer "Full Medical Underwriting," where they assess the risk and give you a definitive "yes" or "no" on specific conditions, rather than a blanket exclusion that leaves you guessing.
Wait Periods and Moratoriums
Another common hurdle is the Período de Carência. Even for people without pre-existing conditions, most Portuguese policies have wait periods of 60 to 90 days for basic care and up to a year for surgeries or childbirth. When a pre-existing condition is involved, these wait periods are often extended, or the condition is permanently excluded. You can find a deep dive into these timelines in our article on Waiting periods (Períodos de Carência) in Portuguese health insurance policies.
| Feature | Local Private Insurance (e.g., Médis) | International Private Insurance (e.g., Cigna) | Public SNS |
|---|---|---|---|
| Pre-existing Coverage | Usually excluded permanently | Sometimes covered with a surcharge | Always covered |
| Medical Exam Required? | Usually just a questionnaire | Questionnaire + sometimes a report | Never |
| Waiting Periods | 60 – 365 days | Variable (can be waived) | None (but long wait lists) |
| Cost Influence | Age and Tier | Health status and Region | Income-based (very low) |
Alternative Paths for Expats with Chronic Health Issues
If you find that local private insurers are giving you the cold shoulder because of your medical history, do not panic. Portugal has several safety nets that ensure you aren't left without care.
The Power of Group Health Insurance
If you are moving to Portugal for work, pay close attention to your benefits package. Many companies in the tech hubs of Lisbon and Braga offer group health insurance through providers like Médis, Multicare, and AdvanceCare: Comparing Top Private Insurers. The "magic" of group policies is that they often waive the medical questionnaire entirely. Because the insurer is covering hundreds of employees, the risk is spread out, and they usually accept all members regardless of their pre-existing conditions. This is arguably the best way for a person with a chronic illness to get full private coverage in Portugal.
Relying on the National Health Service (SNS)
It is a common misconception that you must have private insurance to survive in Portugal. The Serviço Nacional de Saúde (SNS) is the public system, and it is legally obligated to treat everyone who is a resident. The SNS does not care about your pre-existing conditions; they will treat your diabetes, your heart condition, or your thyroid issues for the same minimal co-payments (or even for free) as any Portuguese citizen.
The strategy many of us veterans use is to register with the local health center immediately. Getting your foot in the door by Registering with the Centro de Saúde: Getting Your SNS Número de Utente is the most important administrative task you’ll do. Once you are in the system, your chronic care is managed by a family doctor (médico de família). While the wait times for non-urgent elective surgeries can be long, the quality of care for chronic disease management is generally high.
Bridging the Gap with Self-Care and Supplements
When your private insurance excludes certain treatments or medications for a pre-existing condition, you might find the out-of-pocket costs at a Portuguese farmácia add up quickly. For managing general wellness and chronic health alongside your medical treatment, many expats turn to specialized retailers. I personally use iHerb to source high-quality supplements and vitamins that are often double the price in local shops or simply unavailable. Maintaining your baseline health through these external resources can reduce the frequency of specialist visits that your insurance might not be covering.
Practical Strategies for Managing Your Health Costs in Portugal
Living here with a pre-existing condition requires a bit of tactical planning. You can't just wing it like you might with a clean bill of health. You need to know which door to knock on for which problem.
The Hybrid Health Strategy
New arrivals are best off thinking of their health in two categories: "Maintenance" and "Crisis." For maintenance of your pre-existing condition, stick to the SNS. The prescriptions are subsidized, often costing just a few euros. For a "Crisis" or a new, unrelated issue—like a sudden ear infection or a sports injury—use your Private Health Insurance in Portugal: Costs, Coverage, and Best Providers. This allows you to bypass the public emergency room wait times while keeping your chronic care costs at almost zero through the public system.
If you find yourself needing to pay for private consultations out-of-pocket because of an exclusion, ask for the "uninsured" or "plan" rate. Many private hospitals have agreements with banks or automobile clubs (like ACP) that provide significant discounts on consultations even if you don't have a formal insurance policy.
Understanding Co-payments and the SNS
Even in the public system, there are small fees called Taxas Moderadoras: Co-payments and Costs in the Public Health System. These are usually very small—think €5 to €15 for a consultation or a test—and they are often waived for people with low incomes or certain chronic illnesses. If your pre-existing condition is something serious like cancer or a rare autoimmune disease, the SNS provides comprehensive, high-tech care that actually surpasses what many private hospitals can offer, as the private sector in Portugal is more focused on elective procedures and minor emergencies.
Don't Let Exclusions Discourage You
It is easy to feel "less than" when an insurance company sends you a letter listing your exclusions. Remember that these exclusions only apply to the private payout. They do not mean you cannot see a private doctor. It simply means you will pay the full price for that specific visit. Since a private specialist visit in Portugal usually costs between €40 and €90, it is often more affordable to just pay out-of-pocket for your chronic condition check-up twice a year than to stress over a rejected insurance application.
By understanding the boundaries of the private market and the strengths of the public system, you can build a health strategy that keeps you safe and financially stable. Portugal is a wonderful place to live, and with the right information, a pre-existing condition is just a minor administrative hurdle, not a barrier to your new life.
Disclaimer
The information provided in this guide is for informational purposes only and does not constitute medical, legal, or financial advice. Healthcare laws and insurance policies in Portugal are subject to change, and you should always consult with a qualified insurance broker or legal professional before making decisions regarding your medical coverage. Ensure you read the specific terms and conditions of any policy you sign.