Do Portuguese landlords require renters insurance (Seguro de Recheio)?
Disclosure: This article contains affiliate links. If you buy through them, we may earn a commission at no extra cost to you. Read our full disclosure.
One of the most confusing moments of moving to Portugal is sitting in a sun-drenched café, staring at a thirty-page rental contract in a language you’re still learning, and wondering why the landlord is asking for "recheio." When I moved to my first apartment in Porto, I spent three nights worrying that I was legally exposed to thousands of Euros in damages. This guide clarifies exactly when Portuguese landlords require renters insurance and how to protect your life in your new home.
Understanding the Legal Requirements for Insurance in Portugal
The short answer to whether renters insurance is legally mandatory in Portugal is no, not by national law. According to the Portuguese Civil Code, the only insurance that is strictly mandatory for residential buildings is fire insurance (Seguro de Incêndio). However—and this is a big "however" for expats—this legal obligation falls squarely on the shoulders of the property owner (the landlord) or the condominium (condomínio) for the structural parts of the building.
As a tenant, you are not legally required by the state to hold a policy. That said, the "law of the land" is often superseded by the "law of the contract." In the current rental market, especially in competitive hubs like Lisbon, Porto, and the Algarve, many landlords now include a specific clause in the Portuguese Lease Contracts (Contrato de Arrendamento): What to Look For that makes a multi-risk tenant policy a prerequisite for signing.
When you use platforms like Uniplaces to find a medium-term stay, you might find that the insurance requirements are already baked into the booking process or clearly outlined in the house rules. Landlords are increasingly protective of their assets, and they want to ensure that if you accidentally overflow a bathtub and ruin the downstairs neighbor’s 18th-century ceiling, there is an insurance company ready to pay the bill rather than a long, drawn-out legal battle with a foreigner who might leave the country.
Seguro de Recheio vs Seguro de Responsabilidade Civil
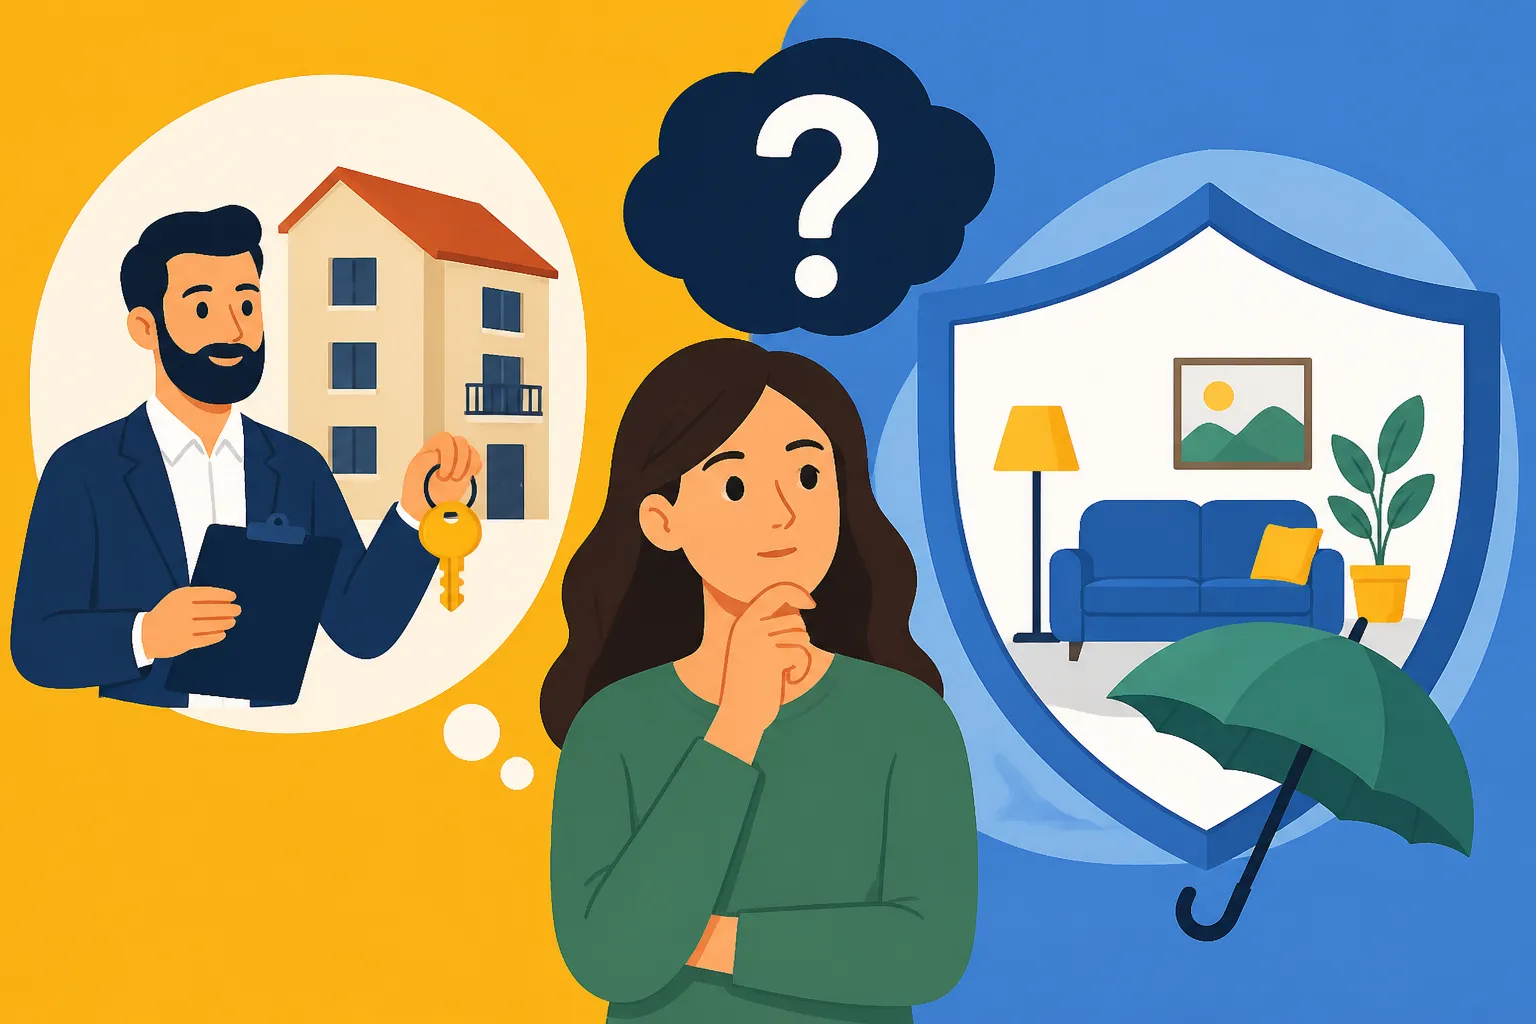
When people talk about "renters insurance" in Portugal, they are usually conflating two different types of coverage. It is vital to understand the difference so you don't overpay or, worse, leave yourself unprotected.
Seguro de Recheio literally translates to "Contents Insurance." This covers the "stuff" inside the apartment. If you have a high-end MacBook, a professional camera, or expensive furniture you brought from home, this is what pays out if there is a fire, a major flood, or a robbery. Many expats think the landlord’s insurance covers their belongings, but it absolutely does not. The landlord’s policy covers the walls, the roof, and the floor—not your designer rug or your electronics.
Seguro de Responsabilidade Civil is "Third-Party Liability Insurance." This is often what the landlord actually cares about. This covers damages you might cause to the building or to other people. For example, if a kitchen fire starts because you left the stove on, or if a pipe under your sink bursts and damages the apartment below, this insurance covers the repairs. In many cases, a "Multi-riscos Habitação" policy will combine both of these.
If you are just arriving and trying to stay connected while you hunt for these policies, using an eSIM from Airalo can be a lifesaver, allowing you to call local insurance brokers or use translation apps on the fly without hunting for a Wi-Fi password at a CTT office.
Common Clauses and the Landlord Perspective
Landlords in Portugal are often wary of the "transient" nature of expats. They know that if major damage occurs, it can be difficult to chase a tenant across international borders. This is why they often insist on insurance as a way to mitigate risk.
You will often see insurance requirements paired with the demand for a guarantor. If you are struggling with this part of the process, it is worth reading up on The Role of the Fiador (Guarantor) and How Expats Can Rent Without One to see your alternatives. Some landlords might accept a higher security deposit in lieu of a guarantor, but they will rarely budge on the insurance requirement if it’s already in the draft.
When reviewing a contract, look for the term "Seguro de Multiriscos." If the contract says "O inquilino deve contratar um seguro de multiriscos," you are contractually obligated to get it. Even if it isn't in the contract, I strongly recommend it for one very specific Portuguese reason: the weather.
Portuguese homes are notoriously cold in the winter and prone to humidity. We often talk about Heating and Insulation in Portuguese Homes: Fighting Winter Cold and Mold because it is a genuine shock to most newcomers. If a pipe freezes and bursts, or if extreme humidity leads to water damage that affects the structure, having an insurance company to mediate can save you from losing your entire security deposit.
Comparing Renters Insurance Options in Portugal
To give you an idea of what you’re looking at, here is a breakdown of typical coverage you might find in a 2026 multi-risk policy for a standard T1 (one-bedroom) apartment in a city center.
| Coverage Type | What is Covered? | Is it Usually Mandatory? |
|---|---|---|
| Fire and Lightning | Damage to your goods from fire or electrical storms. | Often required by contract. |
| Water Damage | Burst pipes or leaks (very common in older buildings). | Highly recommended. |
| Theft/Robbery | Stolen items from inside the home. | Optional but wise. |
| Liability (RC) | Damage you cause to neighbors or the building. | Almost always required by landlords. |
| Aesthetic Damage | Costs to match tiles or paint after a repair. | Often an optional add-on. |
Most basic policies for a T1 apartment will cost you between €80 and €150 per year. It is a small price to pay for the peace of mind it provides, especially when you are navigating Renting an Apartment in Portugal: Contracts, Fees, and Tenant Rights for the first time.
Why Expats Need Contents Insurance More Than Locals
As an expat, your "recheio" or contents are often more valuable than those of a local student. You likely have high-end laptops for remote work, perhaps some imported kitchen gadgets, or a collection of tech you bought via Amazon Spain because it was easier than navigating local shops.
If there is a break-in—which, while rare in Portugal, does happen in tourist-heavy areas of Lisbon and the Algarve—the cost to replace your gear out of pocket would be staggering. Furthermore, many Portuguese insurance policies include "Assistance at Home." This can be a godsend when you need an emergency plumber at 10 PM and your Portuguese isn't yet fluent enough to find one on a local directory.
I remember my second year in Lisbon when a massive storm hit. The "waterproof" windows in my old Alfama flat decided they were actually sieves. My rug was ruined, and my work desk was warped. Because I had a €95-a-year policy, the insurance company handled the claim within three weeks. Without it, I would have been arguing with a landlord who would have likely blamed me for leaving the shutters open.
How to Get Your Policy and What to Prepare
Getting a policy is surprisingly easy and can often be done entirely online. You will need:
- Your NIF (Tax Identification Number).
- The address of the property.
- The approximate value of your belongings.
- The year the building was constructed (this affects the premium).
Pro tip: When you pay your first premium, make sure to ask for the receipt with your NIF on it. This is a recurring theme in Portuguese life. We always suggest Getting your NIF printed on your supermarket receipt for IRS tax benefits because those small deductions add up, and insurance premiums can sometimes be part of your deductible expenses depending on your tax residency status.
Once you have your policy, you must send a copy of the "Apólice" (the policy document) to your landlord. They will keep this on file. If you fail to renew it, and the contract stipulates it as a requirement, it could technically be used as grounds for contract termination, though this is extreme and rare.
Dealing with Maintenance and Claims
The biggest friction point between landlords and tenants in Portugal is maintenance. The landlord is responsible for structural issues, while the tenant is responsible for "wear and tear." Insurance helps bridge the gap when a "wear and tear" accident turns into a structural problem.
If you do have to make a claim, document everything. Take photos of the damage immediately. If it's a water leak, keep the broken pipe if the plumber replaces it. In Portugal, the "Livro de Reclamações" (Complaint Book) exists for businesses, but for landlord disputes, your insurance company’s legal protection department is your best friend.
If you are dealing with a particularly difficult move-out and are worried about How to get your rental deposit (Caução) back: Move-out cleaning tips for Portugal, having a record of your insurance and any claims made can prove that you were a responsible tenant who maintained the property according to the contract.
Practical Steps for New Arrivals
If you are just landing in Portugal, don't rush into the first insurance policy offered by your bank. Banks often have the highest commissions. Shop around with specialized companies like Tranquilidade, Fidelidade, or Médis.
- Check the contract first: See if the landlord has specified a minimum liability amount (usually €50,000 or €100,000).
- Value your gear: Don't under-insure your electronics. Today, the cost of tech has risen, and you want replacement value, not depreciated value.
- Invest in prevention: While insurance is great, preventing a claim is better. Buy a good dehumidifier. You can find the Best dehumidifiers to buy in Portugal to prevent winter wall mold in our dedicated guide—it’s the best €200 you’ll spend in this country.
- Keep your receipts: For any major purchase, keep the digital receipt. If you have a claim, the insurance adjuster will want proof of what you paid.
Living in Portugal is a dream, but the administrative hurdles can feel like a nightmare. By securing a solid Seguro de Recheio, you’re not just satisfying a landlord; you’re building a safety net that lets you enjoy those sunset views over the Tagus without worrying about what’s happening back at the flat.
Disclaimer
The information provided in this guide is for general informational purposes only and does not constitute legal, financial, or professional insurance advice. While we strive to keep the information up to date, laws and market practices in Portugal can change rapidly. Always consult with a licensed insurance broker or a legal professional before signing a rental contract or purchasing an insurance policy to ensure it meets your specific needs and complies with current Portuguese legislation.