US Expats: Do Portuguese banks report my balance directly to the IRS via FATCA?
Disclosure: This article contains affiliate links. If you buy through them, we may earn a commission at no extra cost to you. Read our full disclosure.
The transition to life in Portugal often comes with a steep learning curve regarding how your financial life follows you across the Atlantic. I still remember the first time a bank clerk at a branch in Chiado looked at my blue passport and immediately pulled out a separate stack of forms, specifically asking for my Social Security number. It is a moment of realization that your financial privacy changes the moment you become an American abroad. This guide breaks down exactly how Portuguese banks handle FATCA, what data actually reaches the IRS, and how to navigate these transparency requirements without fear.
Understanding the FATCA Framework in Portugal
The Foreign Account Tax Compliance Act (FATCA) is a federal law from the United States that requires foreign financial institutions to report the assets and identities of US persons to the US Treasury. Many expats mistakenly believe that a local bank in Lisbon or Porto is simply being difficult when they ask for a Social Security number or a W-9 form. In reality, Portugal has signed a "Model 1" Intergovernmental Agreement (IGA) with the United States. This means the reporting is not a choice for the bank; it is a mandatory legal framework enforced by the Portuguese government.
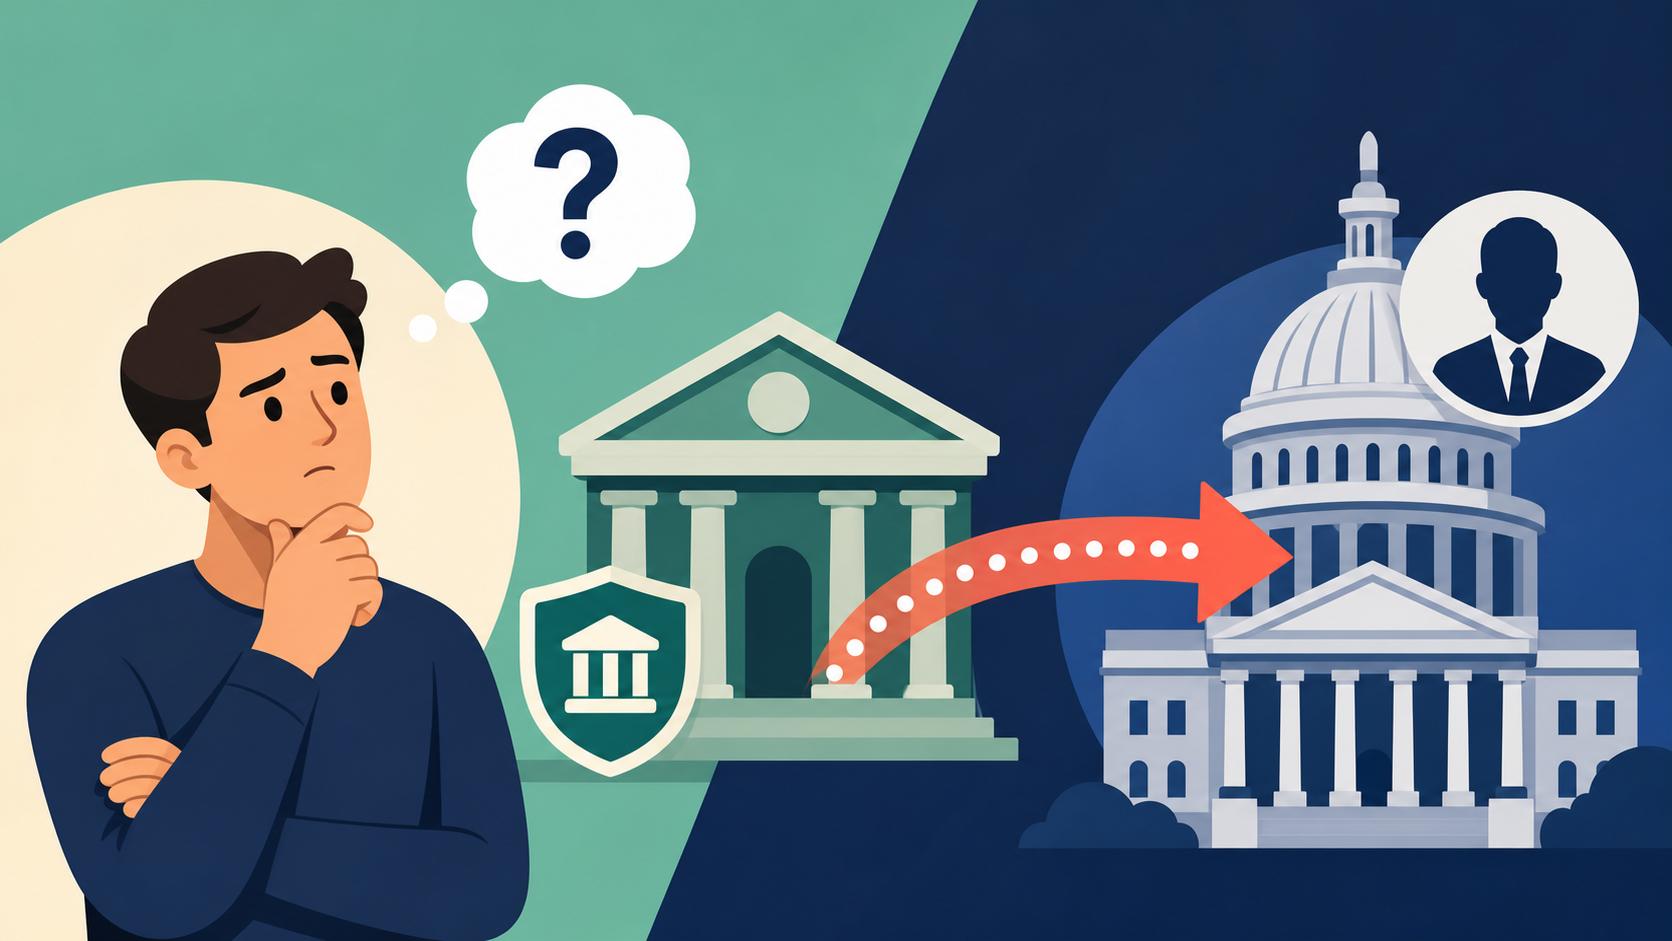
Under this Model 1 agreement, Portuguese banks do not actually send your data directly to the IRS. Instead, they report your account information to the Portuguese Tax Authority, known as the Autoridade Tributária e Aduaneira (AT). The AT then bundles this information and exchanges it with the IRS. This administrative layer is supposed to ensure that data protection laws are respected, but for you, the end result is the same: the IRS will eventually know the year-end balance of your accounts. This is a core component of Money and Finance in Portugal: The Ultimate 2026 Guide for Expats that every American must understand before transferring large sums of money.
The primary reason this system exists is to prevent offshore tax evasion. Because the US taxes based on citizenship rather than just residency, the IRS wants to ensure you aren't hiding income in a Portuguese savings account. While it feels like an invasion of privacy, it is a standard part of the banking experience for US citizens in almost every country today. If you are currently Opening a Bank Account in Portugal: Best Banks for Foreigners and Expats, you should expect these questions as part of the "Know Your Customer" (KYC) process.
What Data is Actually Reported and When
Not every single cent you spend at a local padaria is reported to Washington. There are specific thresholds and types of information that trigger the reporting mechanism. Generally, if you are a US person with a bank account in Portugal, the bank is looking for accounts that exceed certain balances, often starting at $50,000, though many banks simply report all accounts held by US citizens to be safe and avoid penalties.
The specific data points shared usually include your full name, address, US Taxpayer Identification Number (usually your SSN), account number, the year-end balance, and the total amount of interest or dividends credited to the account during the year. This information is critical for the IRS to cross-reference with your Form 8938, which is the FATCA reporting form you file with your annual tax return. If there is a massive discrepancy between what the Portuguese bank reports and what you declare, it can trigger an audit.
It is also important to note that this reporting applies to more than just traditional checking accounts. Savings accounts, term deposits, and even certain types of life insurance policies or investment accounts are subject to FATCA. Even if you are focusing on Portuguese Taxes for Expats: IRS, Tax Residency, and Filing Deadlines, you cannot ignore the US side of the equation. The transparency is bidirectional; while you report your income to Portugal, your assets are being reported back to the US.
FATCA vs FBAR: The Twin Reporting Requirements
A common point of confusion for new arrivals is the difference between FATCA and the FBAR (Foreign Bank and Financial Accounts Report). While both involve telling the US government about your money in Portugal, they are governed by different laws and sent to different departments. FATCA (Form 8938) is sent to the IRS with your tax return, while the FBAR (FinCEN Form 114) is sent to the Financial Crimes Enforcement Network.
The FBAR has a much lower threshold. If the aggregate value of all your foreign accounts—including your Portuguese bank, a Wise account used for transfers, or even a digital wallet—exceeds $10,000 at any point during the calendar year, you must file an FBAR. Note that this is an aggregate total. If you have $6,000 in a Millennium bcp account and $5,000 in a Wise account, you have crossed the threshold. This is a common trap for those US Expats in Portugal: FATCA, FBAR, and Avoiding Double Taxation who forget to count every digital "bucket" of money.
| Feature | FBAR (FinCEN 114) | FATCA (Form 8938) |
|---|---|---|
| Reporting Threshold | $10,000 (Aggregate at any time) | $50,000 – $400,000 (Depends on status) |
| Where to File | FinCEN (Online Portal) | IRS (With Tax Return) |
| Who Reports? | You (The Individual) | You AND the Financial Institution |
| Penalties | Up to $10,000+ per non-willful violation | $10,000 to $50,000 per year |
| Includes Crypto? | Generally No (currently) | No (currently) |
The Investment Trap: PFICs and Portuguese Funds
While your checking account balance being reported is mostly an administrative annoyance, the reporting of investment accounts can lead to a financial catastrophe known as the Passive Foreign Investment Company (PFIC) rules. Most Portuguese mutual funds, ETFs, and even some pension products are classified as PFICs by the IRS. The US government dislikes these because they believe they are used to defer taxes.
If your Portuguese bank reports that you hold these types of assets, you may be subject to extremely high tax rates (often exceeding 50%) and complex annual reporting requirements on Form 8621. Many expat-focused advisors suggest that Americans in Portugal avoid local investment funds entirely and stick to US-based brokerage accounts or individual stocks. If you are using a platform like Trade Republic to save or invest while living in Lisbon, you must ensure you are only buying individual stocks or US-domiciled ETFs to avoid the PFIC nightmare.
This is where Finding an English-Speaking Certified Accountant (Contabilista Certificado) becomes essential. You need someone who understands both the Portuguese Modelo 3 and the US reporting requirements. If you inadvertently buy a Portuguese fund because your bank manager recommended it for tax efficiency in Portugal, you might find that any tax savings here are wiped out ten times over by US penalties.
Digital Assets and Crypto Reporting
The landscape for digital assets is shifting rapidly. Currently, the IRS and the Portuguese AT are increasing their scrutiny of cryptocurrency holdings. If you are using Binance or other exchanges while resident in Portugal, do not assume you are "off the grid." Portugal has introduced its own crypto tax regime, and exchange of information agreements are expanding to include digital assets.
While crypto wallets themselves aren't typically reported under FATCA in the same way a bank account is, any linked bank accounts used to fund those wallets will be visible. Furthermore, if you are a high-net-worth individual, the IRS expects you to answer the "digital asset question" on the first page of your 1040. When Filing the Annual IRS Tax Return (Modelo 3): Deadlines and Process, remember that the Portuguese authorities are also becoming much more proficient at tracking on-chain activity to ensure you are paying capital gains on your trades.
Using platforms like Binance requires a clear paper trail. If you eventually want to use your crypto gains to buy property in Portugal, the bank will ask for a rigorous "Source of Funds" report. If your reported FATCA balances and your sudden influx of cash for a house deposit don't align, you could face significant delays or even a frozen account.
Which Portuguese Banks Are Most "US-Friendly"?
Not all Portuguese banks want to deal with the headache of FATCA reporting. Some smaller, regional banks may simply refuse to open accounts for US citizens because the compliance costs are too high. However, the major players are well-equipped to handle American clients. Millennium bcp and its digital-first subsidiary, ActivoBank, are among the most popular choices for expats. They have streamlined the W-9 process and offer English-language interfaces.
When you open your account, be prepared to provide your Social Security Number immediately. If you try to withhold this, the bank is legally required to refuse the account or close it shortly after. If you are also in the process of Registering with the Centro de Saúde: Getting Your SNS Número de Utente, you are likely already carrying around your passport and NIF (tax number); just add your US Social Security card or a digital copy to your "moving folder."
Another factor to consider is how these banks interact with your US-based accounts. If you are Transferring Money to Portugal: Saving on Exchange Rates and Fees, using a service like Wise is often more efficient than a direct SWIFT transfer between a US bank and a Portuguese one. Wise is also FATCA-compliant and will request your tax details, ensuring that your international transfers don't raise red flags with either the AT or the IRS.
Building a Strategy for Financial Compliance
Living as a US expat in Portugal is incredibly rewarding, but the price of entry is a commitment to transparency. You should never try to "hide" a bank account from the IRS. The risk of the AT sharing your data via FATCA is nearly 100% over a long enough timeline. Instead, focus on keeping your reporting clean and synchronized.
- Keep Records: Save your year-end bank statements (Extratos de Fim de Ano) from every Portuguese account. These will show the exact figures the bank is reporting to the AT.
- Use a Specialized Accountant: Do not use a generic tax preparer in the US who doesn't understand foreign exclusions (FEIE) or foreign tax credits (FTC).
- Monitor Your Credits: If you are Building Credit in Portugal: Do Credit Scores Matter for Mortgages?, remember that your debt isn't reported to the IRS, but the assets in any linked collateral accounts certainly are.
- Stay Updated: Tax laws in both countries change. In 2026, the thresholds for reporting may shift, or new asset classes may be included in the IGA exchange.
Ultimately, the fact that Portuguese banks report your balance is just a reality of modern expat life. It doesn't mean you will owe more tax—thanks to the US-Portugal Tax Treaty, you can usually avoid double taxation—but it does mean you must be diligent with your paperwork. Portugal is a wonderful place to call home, and once you get the FATCA and FBAR rhythms down, they become just another annual administrative task, much like renewing your resident permit or paying your car tax.
Disclaimer
This guide is for informational purposes only and does not constitute legal, financial, or tax advice. Tax laws, particularly those involving international treaties and the IRS, are subject to frequent change. You should always consult with a qualified tax professional who specializes in US expat taxation and Portuguese law before making any financial decisions.