How to Avoid Double Taxation Between the US and Portugal
Disclosure: This article contains affiliate links. If you buy through them, we may earn a commission at no extra cost to you. Read our full disclosure.
The moment you realize that moving to Portugal doesn't mean you stop owing the IRS is a cold shower for any American expat. I remember sitting in a sunny café in Cascais, looking at a Portuguese tax bill and a US tax software prompt simultaneously, feeling like I was being squeezed from both sides. This guide breaks down the US-Portugal tax treaty to ensure you never pay the same Euro twice.
The Foundation of Tax Residency in Portugal
Understanding where you are legally required to pay tax is the first hurdle. For most Americans, the confusion starts because the United States is one of the only countries that taxes based on citizenship, regardless of where you live. Portugal, like most of the world, taxes based on residency. This creates a situation where two different nations have a legal claim to a slice of your income.
In Portugal, you are generally considered a tax resident if you spend more than 183 days in the country during a 12-month period. This doesn't have to be a consecutive stretch; the Autoridade Tributária e Aduaneira (Finanças) tracks your cumulative presence. Even if you stay fewer than 183 days, you can be deemed a resident if you maintain a primary residence in Portugal that suggests an intention to stay permanently. This is often triggered when you sign a long-term lease or buy property. Once you are a resident, you must report your worldwide income to the Portuguese authorities.
Before you even start worrying about the IRS, you need to ensure your local paperwork is in order. This starts with Becoming a Tax Resident in Portugal: The 183-Day Rule Explained and ensuring your NIF (Número de Identificação Fiscal) address is updated. If you are still listed as a non-resident on your NIF but are living here full-time, you might be incorrectly taxed or miss out on certain deductions. Getting this right is the baseline for avoiding the double-dipping of tax authorities.
Navigating the US-Portugal Tax Treaty
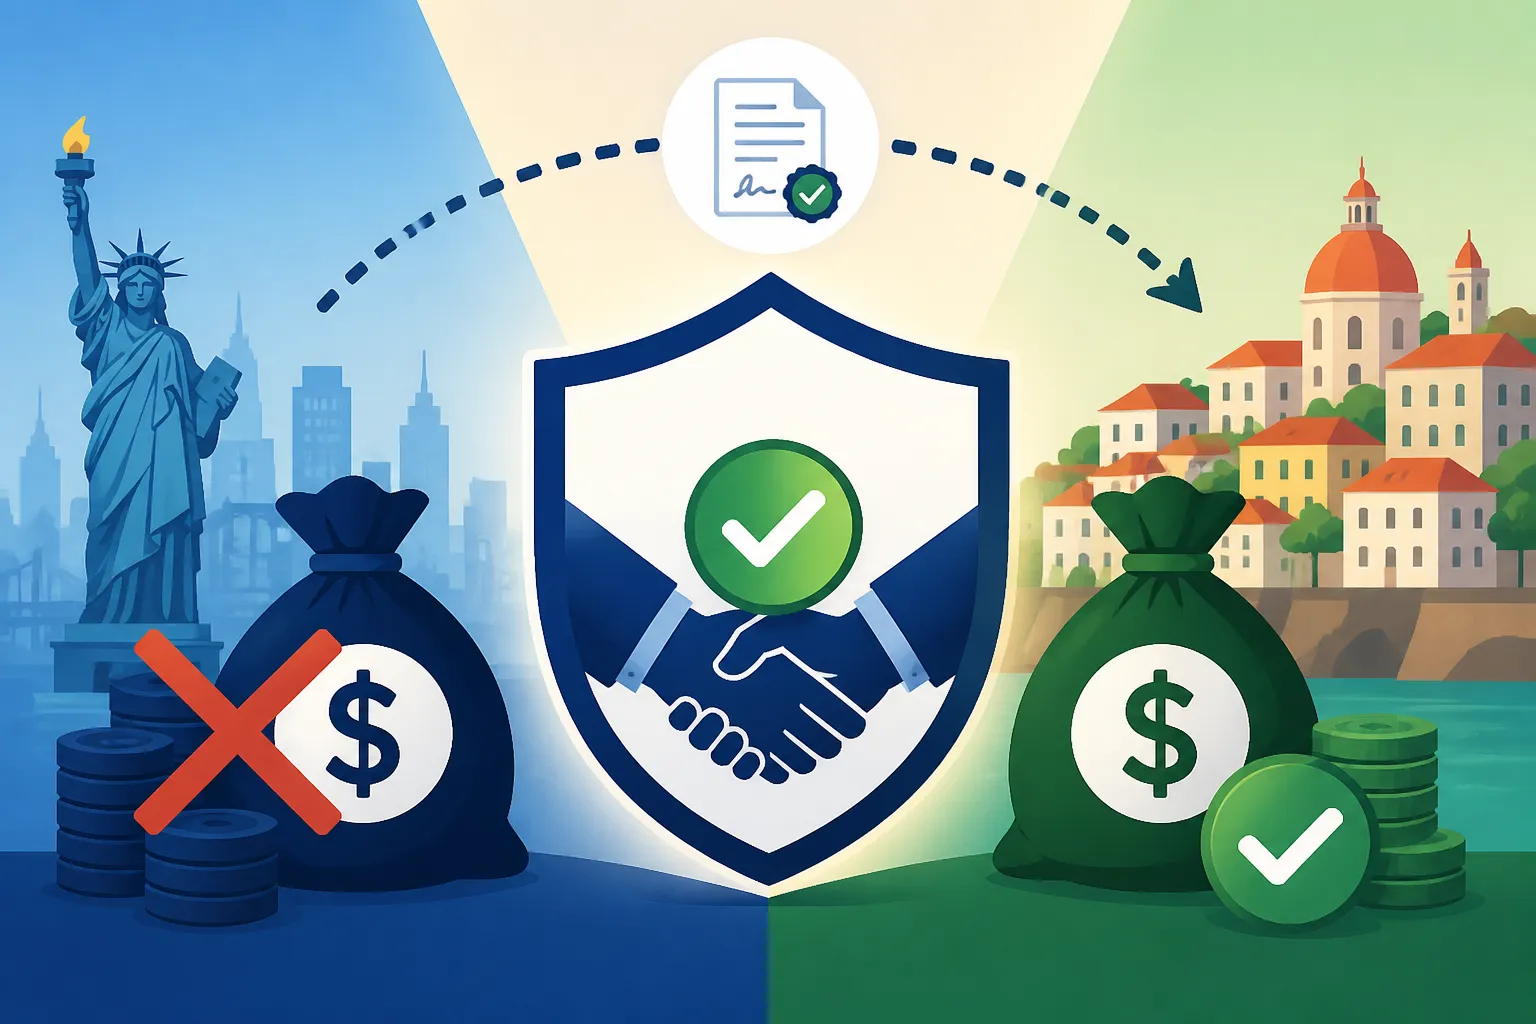
The primary shield against paying full tax to both countries is the Convention between the United States of America and the Portuguese Republic for the Avoidance of Double Taxation. This treaty was signed in 1994 and serves as a set of "tie-breaker" rules. It dictates which country has the primary right to tax specific types of income, such as social security, dividends, or rental income from property.
Under the treaty, the country where the income is "sourced" usually gets the first bite. For example, if you own a rental property in Florida but live in Lisbon, the US has the primary right to tax that rental income. However, because you are a Portuguese resident, you must also report that income on your Filing the Annual IRS Tax Return (Modelo 3): Deadlines and Process in Portugal. The treaty then allows you to take a credit in Portugal for the taxes you already paid to the US.
This is where things get granular. The treaty has specific articles for different scenarios. Article 19, for instance, covers government service, while Article 20 covers pensions. Navigating these requires a high level of organization. I’ve found that using specialized services like Taxes for Expats is often the only way to ensure these treaty benefits are actually claimed on your US return. Without specifically citing the treaty on your Form 8833, the IRS may simply assume you owe the full amount.
Strategies to Mitigate Double Taxation
For Americans working abroad, there are two main tools provided by the IRS: the Foreign Earned Income Exclusion (FEIE) and the Foreign Tax Credit (FTC). Choosing between them is not a "one-size-fits-all" decision and can significantly impact your long-term wealth.
The FEIE (Form 2555) allows you to exclude a certain amount of your foreign earnings from US taxable income—roughly $120,000, adjusted for inflation. This is great if you live in a low-tax country, but Portugal is not exactly a low-tax jurisdiction. If you are paying high Portuguese tax rates, the FTC (Form 1116) is often a better route. The FTC gives you a dollar-for-dollar credit against your US tax bill for the taxes you paid to the Portuguese government.
| Feature | Foreign Earned Income Exclusion (FEIE) | Foreign Tax Credit (FTC) |
|---|---|---|
| Primary Form | Form 2555 | Form 1116 |
| Income Type | Earned income only (salary, wages) | Earned and passive income |
| Benefit | Excludes up to a limit (~$120k) | Dollar-for-dollar credit for PT tax |
| Eligibility | Physical Presence or Bona Fide Residence | Any foreign taxes paid or accrued |
| Child Tax Credit | Cannot claim refundable portion | Can usually claim full credit |
| Future Impact | Revoking it can ban use for 5 years | More flexible year-to-year |
When you use the FTC, you often end up owing $0 to the IRS because Portuguese tax rates are generally higher than US federal rates. However, you still have to go through the motions of filing. Many expats get into trouble because they thought "$0 owed" meant "no need to file." That is a dangerous mistake. To manage these cross-border payments and keep your records clean, many of us use Wise to move funds between US and Portuguese accounts, ensuring we have clear digital trails for our accountants.
The Role of NHR and NHR 2.0 in Tax Planning
Portugal’s Non-Habitual Resident (NHR) program has long been the "holy grail" for expats. While the original NHR is being phased out for new residents, the transition to the NHR 2.0 (IFICI) Tax Regime: Eligibility, Flat 20% Tax, and Rules in 2026 still offers significant benefits for those in "high-value" professions. For Americans, the NHR creates a fascinating, if complex, dynamic.
Under the NHR, certain foreign-sourced incomes are exempt from Portuguese tax if they could be taxed in the source country under a tax treaty. Because the US-Portugal treaty says the US could tax your US dividends or rental income, Portugal often exempts them for NHR holders. This is one of the few times where you might actually pay the lower US tax rate instead of the higher Portuguese rate.
However, if you are an American working remotely for a US company, Portugal will still view that as Portuguese-sourced income because the work is being physically performed on Portuguese soil. In this case, you would likely be taxed at the 20% NHR flat rate (if eligible) or the standard progressive rates. You would then use the FTC on your US return to offset those Portuguese taxes. It is a delicate dance of Portuguese Taxes for Expats: IRS, Tax Residency, and Filing Deadlines that requires checking both boxes every single year.
Reporting Requirements: FBAR and FATCA
Double taxation isn't just about the money you pay; it's about the information you disclose. The US government is incredibly protective of its tax base and requires two major disclosures that catch many off-guard: the FBAR and Form 8938 (FATCA).
The FBAR (Foreign Bank and Financial Accounts Report) is required if the total value of all your foreign accounts exceeds $10,000 at any point during the calendar year. This isn't just your checking account at Millennium bcp; it includes savings, investment accounts, and even certain life insurance policies. The penalties for failing to file an FBAR are draconian—often starting at $10,000 per non-willful violation.
If you have significant assets, you also have to deal with FATCA. This is part of your annual tax return (Form 8938) and has higher thresholds than the FBAR. Portuguese banks are now required to report the balances of accounts held by US citizens directly to the IRS. This makes "hiding" an account virtually impossible. When you are Opening a Bank Account in Portugal: Best Banks for Foreigners and Expats, you will inevitably be asked to sign a W-9 form. This is the bank’s way of complying with US law.
Practical Steps for US Expats in Portugal
To successfully navigate this landscape, you need a workflow. First, keep meticulous records of every Euro spent and earned. I recommend keeping a separate folder for your "Recibos Verdes" (if you're a freelancer) and any bank statements showing tax withholding.
Second, consider your timing. The US tax year is the calendar year (January to December), and the Portuguese tax year is the same. However, the filing deadlines differ. The US deadline is April 15th (with an automatic extension to June 15th for expats), while the Portuguese IRS (IRS stands for Imposto sobre o Rendimento de Pessoas Singulares) is typically filed between April 1st and June 30th. This overlap can be stressful, but it allows you to finalize your Portuguese taxes before claiming the credit on your US return.
Third, look into the specific requirements for your visa. For example, if you are here on a D7 Passive Income Visa Portugal: 2026 Requirements and Step-by-Step Process, your passive income (like Social Security or a 401k) will be taxed differently than a digital nomad on a D8 visa. Social Security, for instance, is generally only taxable in the country of residence under the treaty, but the US often reserves the right to tax its own citizens under a "saving clause." This is where a firm like Taxes for Expats becomes invaluable, as they understand these obscure treaty overrides that a local Portuguese accountant might not know.
Managing the Financial Logistics
Moving money to pay these taxes is its own hurdle. When you owe the IRS, you likely want to pay from a US-based account to avoid international wire fees and poor exchange rates from traditional banks. Conversely, when paying Finanças, you need Euros in a Portuguese account.
I have found that Transferring Money to Portugal: Saving on Exchange Rates and Fees is best handled through Wise. It allows you to maintain a balance in both USD and EUR, making it easy to pay your US tax bill and your Portuguese quarterly social security contributions without losing 3-5% in hidden bank fees. In fact, keeping your finances "multi-currency" is almost a requirement for an American in Portugal.
Finally, do not forget about state taxes. Just because you moved to Lisbon doesn't mean your home state has let you go. States like California, New York, and Virginia are "sticky" and may continue to demand tax returns unless you can prove you have completely severed ties. Moving your voter registration, driver's license, and financial "domicile" to a tax-free state like Florida or South Dakota before you move to Portugal is a common veteran expat move.
Understanding the US-Portugal Tax Treaty 2026
The tax landscape is always shifting. We are seeing increased cooperation between the US and Portugal regarding digital assets and remote work. If you are involved in crypto, you must be aware of US Expats in Portugal: FATCA, FBAR, and Avoiding Double Taxation specifically as it relates to the 28% Portuguese capital gains tax versus the US 15-20% rate.
The treaty protects you, but it doesn't automate your life. You are the one who must prove to the IRS that you paid tax in Portugal, and you must prove to Finanças that your US income is "foreign-sourced." It feels like a part-time job sometimes, but the reward—living in one of the most beautiful, safe, and welcoming countries in the world—is well worth the paperwork.
Summary of Essential Forms for US Expats
- IRS Form 1040: Your standard annual US income tax return.
- Form 2555 (FEIE): Used to exclude foreign earned income.
- Form 1116 (FTC): Used to claim credit for taxes paid to Portugal.
- Form 8833: Used to disclose a treaty-based return position.
- FinCEN Form 114 (FBAR): Reporting your Portuguese bank account balances.
- IRS Form 8938 (FATCA): Reporting foreign financial assets (higher thresholds).
- Portuguese Modelo 3: Your annual Portuguese tax return where you report worldwide income.
By staying on top of these forms and using the right tools, you can enjoy your bica and pastel de nata without the looming fear of a dual-tax audit. It takes a year or two to get the rhythm down, but once you do, the system works.
Money and Finance Disclaimer
The information provided in this article is for educational and informational purposes only and does not constitute professional tax, legal, or financial advice. Tax laws in both the United States and Portugal are subject to frequent change and complex interpretation. Always consult with a qualified tax professional or certified accountant who specializes in cross-border taxation for US expats before making any financial decisions or filing tax returns. Personal circumstances vary, and the application of tax treaties can differ significantly based on individual residency status and income types.